When is Enough an Enough?
We just published this 12-page report on Virtuix (VTIX) and it’s fantastic Virtual Reality Experience. Fantastic as defined by users testimonials.
They’ve only had $15 million in revenues over the past few years, but they just announced they became a Facebook/META partner – which could super-charge both their user and revenue growth.
There are only 15 companies in the world who have been allowed into the partnership: Made for Meta Partners
This partnership open the doors to META’s 20 million (give or take) users of their Quest VR Headsets (formally Oculus).
Meta’s Share of the Headset Market.
The way it works is like this:
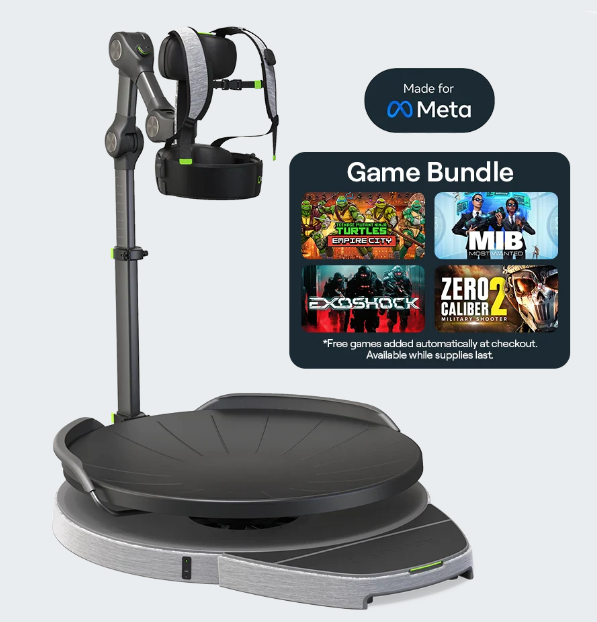
75+ games that work on the META Quest headset, now integrate seamlessly with the Virtuix Omni One Virtual treadmill.
These individuals already bought and own the Quest headset. He or she already bought and own software, to play on the headset. Virtuix didn’t have to make a headset and didn’t have to make the software game.
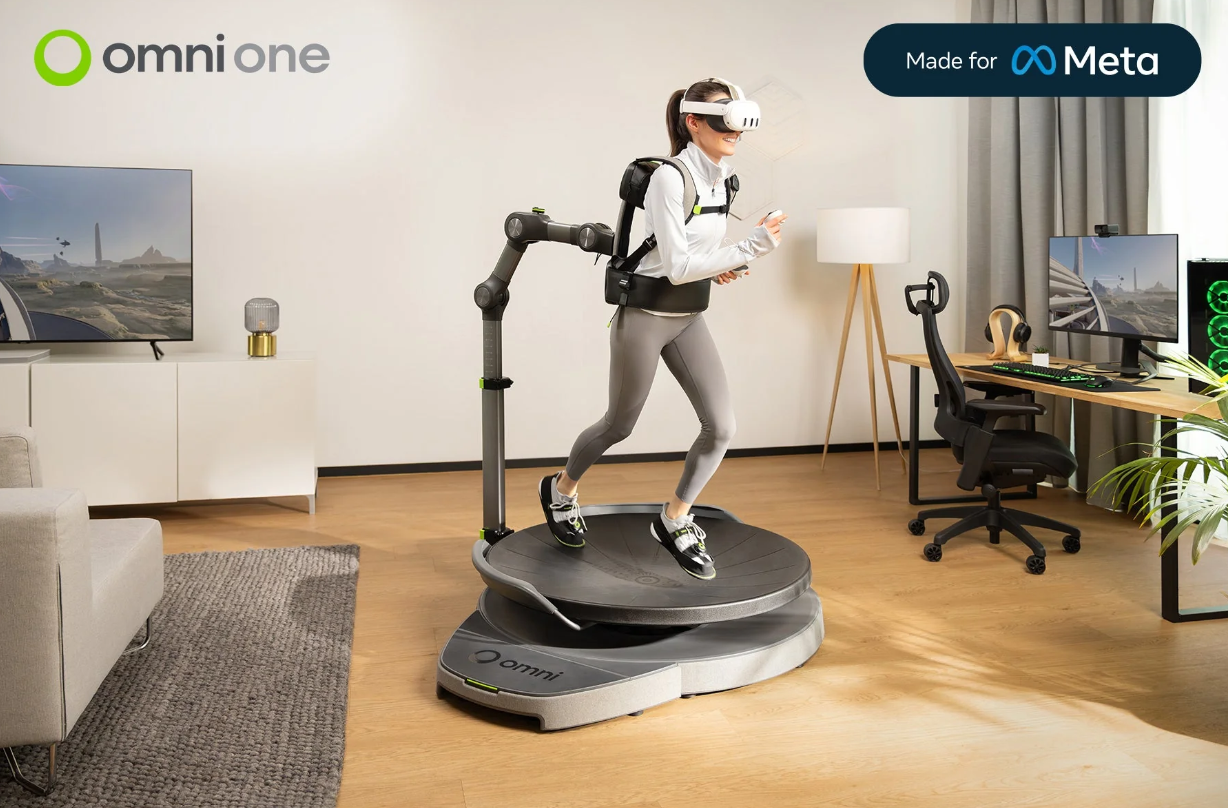
What they did make, is a revolutionary treadmill that lets those Quest users dramatically improve their VR experience on games they already own, using a headset they already own – by letting them walk, run, crouch, or jump in 360 degrees, with real-world motion translating directly into their game.
Basically it puts them “in the game.”
It is a feat of modern hardware engineering that took Virtuix over $40 million in capital and a decade of R&D to create – yet the public market is pricing the entire platform at less than the cost to build it.
It’s a long weekend read, but if you take the challenge you’ll know more about Virtuix reading these five articles and ‘how to’ videos, than 75% of its current panicked and/or ‘lost patience’ shareholder base. Insiders own the other 25%.
Of course it the share price could go lower, but if a press release comes out in the next few months (think around Christmas) that Omni One was grabbing a statistically significant (a biotech term lol) number of Facebook/META users – investors will do the following math and then sky is the limit.
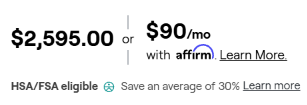
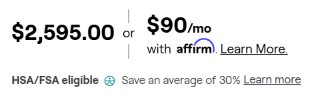
Here’s the simple math: The Omni One platform retails for $2,595, or $90 a month through Affirm.
10,000 Quest Users = $25,950,000
36,000 Quest Users = $93,420,000 (current capacity)
100,000 Quest Users = $259,500,000
500,000 Quest Users = $1,297,500,000
1 Million Quest Users = $2,595,000,000
..and we can stop there. 1 million users by the way is 5% of 20 million users.
We said “enough is enough” a week ago, at $1.20 (ouch).
Then after that ‘brilliant’ light bulb went off, we spent the weekend familiarizing ourselves with the entire gaming sector and the virtual reality gaming sector. Gaming experts, we are not, though we will get there.
Keeping in mind, the only games we’ve ever played are bar-based, not living-room-based—like darts, table shuffleboard, and the infamous Shake-of-the-Day dice.
For those of you not familiar with the dice game (it’s for old-timers like us), the premise is pure, low-stakes tavern gambling. You pay $1 to the bartender to buy into the running kitty, grab a leather cup with five or six dice, and give it one massive shake. If you hit the miracle roll—usually all sixes or five-of-a-kind—you walk away with the entire cash pot. If you miss, your dollar stays in the jar, bloating the pot for the next roller.
It’s primarily for regulars, because walking into a bar for the first time, rolling, and walking away with say a $312 kitty, which you never contributed to, is just so wrong. It happened to us once (okay, three times), but with proper bar etiquette, we settled for a free round (or was it three rounds?) of drinks.
If you want to talk about rolling the dice on a potentially monstrous cash pot, let’s talk about catching the falling knife on Virtuix Holdings Inc. (VTIX). As we’ve reported earlier, it looks like a bottom-fisher’s dream play.
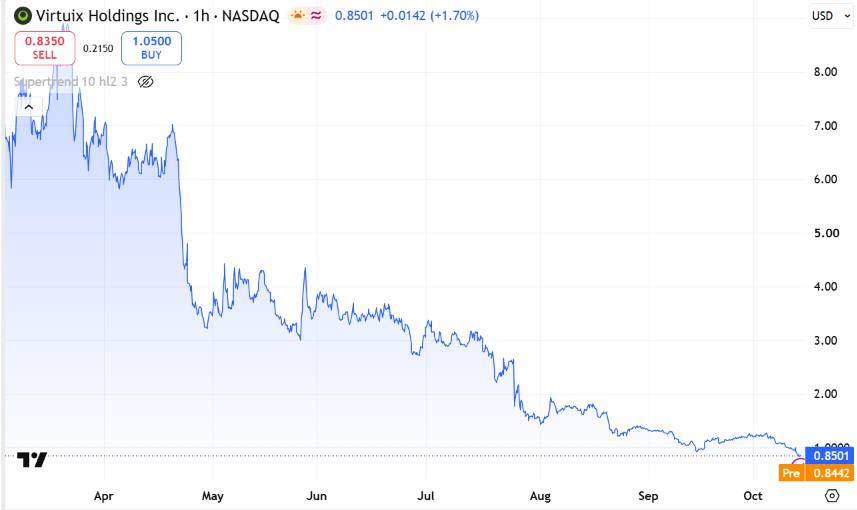
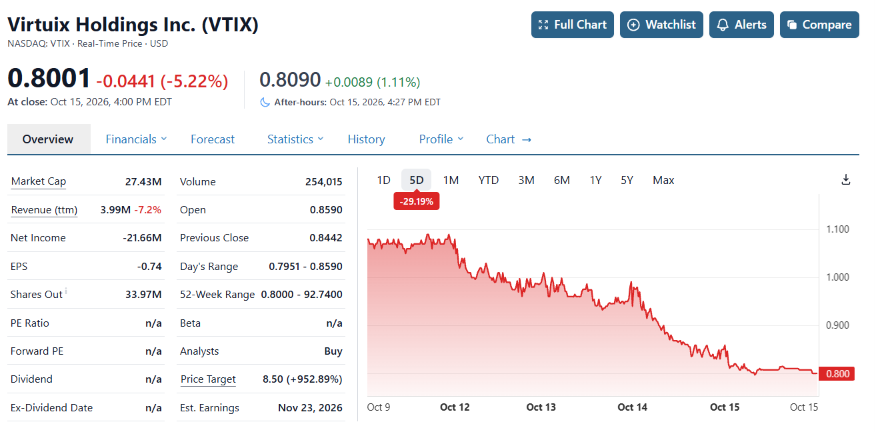
A mere week ago, we recommended bottom fishing this stock at $1.20, after watching it crater from an eye-watering all-time high of $92.14 – less than a year ago. Walking into the VR hardware market right now feels exactly like stepping up to a strange bar counter and calling a high-stakes bet (but less than $1.00) on the very first shake. The stock has continued to slide to around $0.80, pushing it deep into micro-cap, high-volatility territory.
However, we aren’t playing a fast round of 7-14-21 dice here. We have a firm 2-year outlook on this play. While the market has heavily punished the stock due to the usual near-term execution worrries, non-strategy related selling pressure. The core fundamentals behind their Omni One full-body VR platform experience remains incredibly sticky. Independent researchers continue to eye a massive multi-use inflection point spanning consumer gaming, fitness, and defense markets going into calendar year 2027. It’s a classic high-risk, asymmetric bet—and we are holding the cup. Do we roll? We think yes.
In addition to learning more about the Virtuix Virtual Reality Treadmill Experience below, we’ll explain (in our opinion) why we think the stock has cratered.
So, come learn with us..
THE GAMING MARKET SECTOR
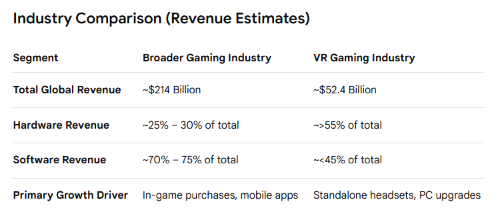
The first thing we learned about the industry is that it’s enormous (and that people need to get out of the house more often!).
Gaming and Virtual (VR) Gaming – Hardware and Software:
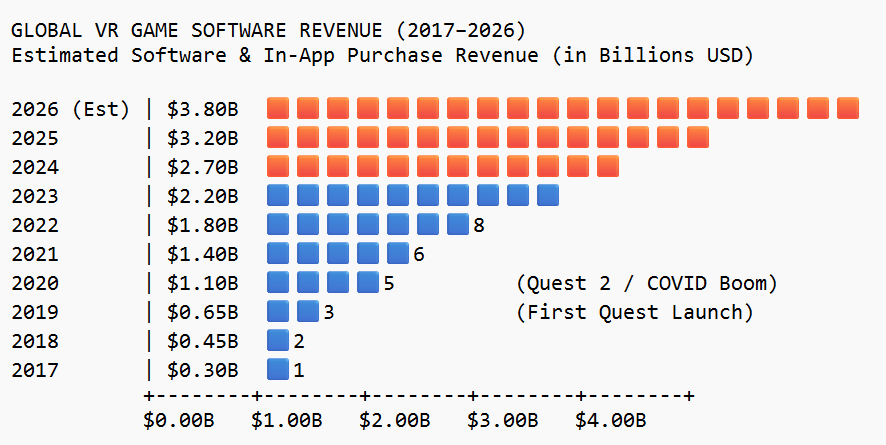
Virtual (VR) Gaming – Software Only:
$3.8 billion last year.
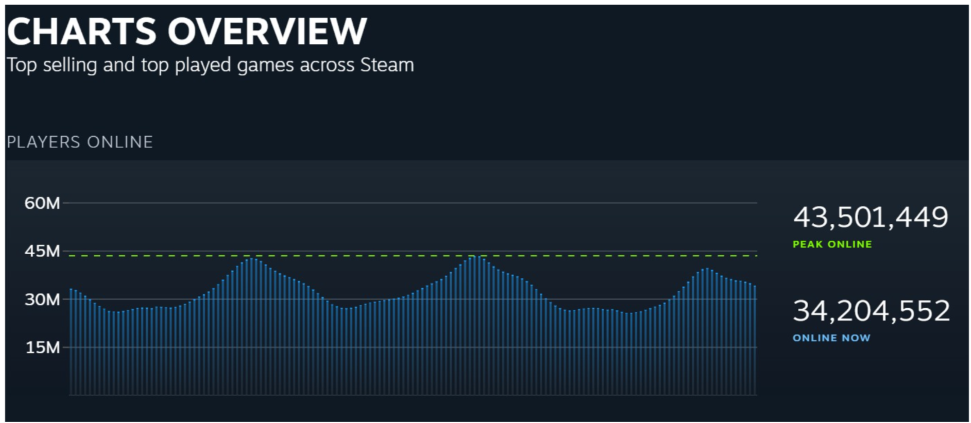
Concurrent Players Chart
Here’s the best chart of all. And it’s mind-boggling.
We triple-checked the numbers for accuracy, because they are so unbelievable, at least to us! We checked mid-day yesterday, while Virtuix was sliding down in price, to boost our confidence.
If you want a sense of the sheer scale of the playground we are dealing with, look no further than Valve’s User Steam platform. Just this past weekend, Steam logged an unbelievable 43.5 million players online simultaneously. That isn’t total accounts—that is the number of people sitting at the global digital bar counter at the exact same time. Valve controls the vast majority of digital PC game sales.
Even if Virtuix’s Omni One platform only captures a tiny fraction of a percent of that broader monster ecosystem over the next two years, the revenue conversion on premium hardware and software subscription additions becomes an explosive asymmetric win.
While the broader tech world estimates that over 200 million people globally have tried or own an XR/VR device, the core gaming market that actively plays VR is estimated at roughly 25 to 30 million active users. Fitness users are now becoming a very real factor in user count, and the Virtuix Experience is sitting in the Cat Bird seat there.
This is Virtuix general target market, with Facebook/META being its (or our) specific target market.
BACK TO THE STORY
The more we read about sector in general, and about Virtuix (VTIX) in particular, the more we get excited. Incredible product + incredible user base = incredible potential. it’s a very simple thesis. The product design is complete, version 3 is done with rave reviews. No worry about a ‘to-be-launched’ date. You can buy one tomorrow.
And we’re not done studying it yet. Subscribe for future updates as we head into the Holiday shopping season.
Ultimately, we are – as we used to say at Drexel Burnham in the 80’s – ‘highly confident‘ through the expected short and mid-term volatility, that we will be right, given time – like a couple years. In fact we could roll the dice that this could be one of our top ideas ever. And we’ve uncovered 14 clients gaining over ten-fold in value since 1995, though they are not a client, yet.
For you, we have put together for your due dilligence efforts, five articles related to Virtuix. Designed to save you time. It took days to compile the following, but only a couple hours to read. Perfect for this weekend.
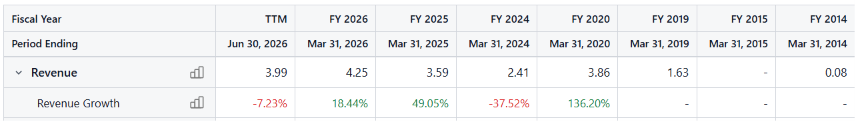
Total Market Cap – just $28.6 million.
- How Virtuix Went Public, and Learn Why we Think it Cratered.
- Eventually, the Smart Money Arrives? Why we Think Virtuix Rebounds.
- Expert Users Describe the Virtuix Experience. Learn How it Works, Without Buying One.
- Original Report: Virtuix’s (VTIX) Full-Body Immersive Game Experience. Learn What we Like About Virtuix.
- Brief History (11 Minutes) of the Virtual Reality Game Business.
- Story of Oculus: a $2 Billion META Acquisition in 2014 Worth $16 Billion Today.
- Recent Charts. Been a Rough Year.
Key Operational Metrics
- 52-Week Range: $0.81 – $92.74
- Current Market Capitalization: $28.82 Million – Peak Valuation $3.1 Billion (for a few minutes)
- Lifetime Sales: $15.82M
- Primary Value Driver: Patent-protected AI-driven VR home gaming and commercial treadmills (Omni One, Omni Pro)
- Consensus Analyst Targets: Recent revisions maintain a highly bullish long-term window, ranging from $7.20 to $8.00 (EGR, Maxim), implying massive recovery upside if execution clears.
HOW THEY WENT PUBLIC, WHY IT CRATERED
First lets look how Virtuix raised the tens of millions needed (it wasn’t cheap), to come up with the very best Virtual Reality Experience on the market today. How they raised the money (Pre-IPO), which in our opinion explains in hindsight, why the stock has cratered. Short story, not operational problems, but rather everyday market confusion. Which tends to rights itself given time. That and new customer count.
Crowdfunding Darling
Virtuix didn’t just use one crowdfunding platform to build its massive retail investor base—they treated equity crowdfunding like a multi-tiered tournament.
CEO Jan Goetgeluk began developing the original Omni treadmill in 2011, motivated by a desire to walk naturally in virtual worlds rather than pushing buttons on a controller.
He launched a Kickstarter for the product in June 2013 that raised over $1.1 million, making it one of the most successful campaigns of its time.
Virtuix has since raised $50 million from high-profile investors including Mark Cuban, several venture funds including Maveron and Scout Ventures, in addition to the equity crowdfunding. These people are hard to fool. They conduct deep due-diligence.
Before debuting on the Nasdaq, Virtuix hit Kickstarter, SeedInvest, and StartEngine across multiple rounds, accumulating over $35 million from a once passionate army of over 10,713 everyday retail backers.
Therein, Lies the Answer to the Question, Why has it Cratered?
The Crowdfunding Campaign Breakdown
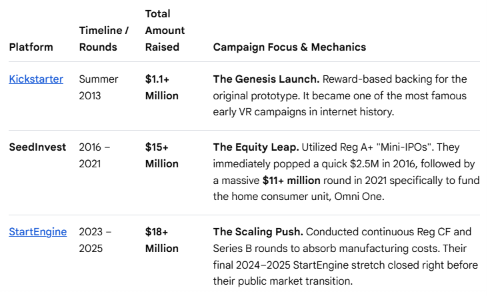
(Note amount raised was year specific, not platform specific. For example, their final crowd-focused push on StartEngine pulled in an additional $3.2 million from over 1,300 everyday investors, successfully pushing their total Series B pool past the $18 million mark. The larger figure includes accredited private investors, venture funds, and Reg D convertible notes, alongside the crowd capital).
The Crowdfunding Cost-Basis Trap
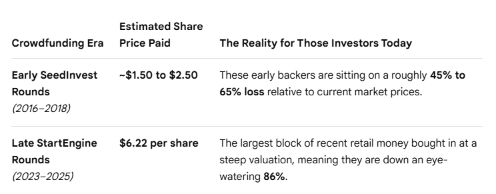
When Virtuix Holdings Inc. (VTIX) went public on the Nasdaq, they officially reported approximately 10,713 stockholders of record. For a newly listed company with a market cap fluctuating around $27–$30 million, having over 10,000 individual shareholders is an incredibly massive, top-heavy retail base of small investors.
To put that in perspective, if you divide their 29.9 million outstanding Class A shares by those 10,713 owners, the average holding is a mere 2,791 shares per person. Many of these shareholders own much less than that. At today’s price of eighty-one cents, the average investor’s remaining stake is worth just about $2,260.
We aren’t dealing with massive institutions deciding whether to trim a multi-million dollar hedge position; we are dealing with thousands of regular folks holding pocket-change positions who got fatigued watching their initial crowd investment slide. When thousands of small accounts decide to clear out their virtual closets at the exact same time, the price is going to completely detach from the actual value of the company’s tech.
The Dream vs. the Reality
Most crowdfund investors don’t invest on a ‘numbers’ basis, they invest on an ’emotional’ basis. They see a start-up in Vodka, they think it can be the next Tito’s (sales of $2.6 billion) and that their $2,000, can grow to $20,000. When they see a start-up in health & fitness, they think it can be the next Peloton which raised $307K on Kickstarter in 2013, with the bike+subscription mode and IPO’d at a $1 Billion + valuation.
When the see a start-up in Virtual Reality, they of course think of Oculus which in 2013 did a reward-based crowdfunding. They sought $250,000 and blew past it in two hours, ultimately raising $2.43 million from 9,522 backers. Less than two years after the Kickstarter campaign, Facebook/META bought Oculus for $2 billion in March 2014.
So when Virtuix did a self-directed IPO (registering shares for pre-ipo investors) the excitement and expectaions were understandably, if not unreasonably high.
Because Virtuix went public via a Direct Listing rather than a traditional IPO, the process worked quite differently from a standard stock debut. In a traditional IPO, investment banks set a fixed price the night before. In a direct listing, an auction takes all buy and sell orders submitted before trading begins and matches them up to find the exact “crossing” price where the maximum number of shares can change hands. Once that equilibrium point is found, the orders cross, the official opening price is set, and regular continuous trading begins. The cross price was $20.75. Meaning all Pre-IPO investors were doing well, if they could get out at that level.
“And up through the ground come a-bubblin’ crude. Oil, that is. Black gold. Texas tea. Well the first thing you know old Jed’s a millionaire.“
Day 1: The Blow-by-Blow Breakdown
A closer look at the data from that chaotic first day highlights how a massive retail imbalance caused the stock to trade erratically:
- The Opening Cross ($20.05): When the opening auction finally crossed, the official price printed at $20.05. This massive premium over where shares were being valued during crowdfunding rounds instantly signaled that retail buy orders were heavily outstripping the available supply in the morning.
- The Algorithmic Spike ($92.74): Because direct listings often start with a very low amount of initial selling volume, the stock suffered from a severe liquidity vacuum. A sudden rush of aggressive buy orders collided with an empty book, causing the price to skyrocket in a chaotic spike all the way to a historic peak of $92.74.
- The Institutional Flush ($13.16): The moment the stock printed that near-$93 level, early backers, and sharp traders immediately recognized the severe overvaluation (at $3 billion). They flooded the market with sell orders to cash out, completely overwhelming the buyers and sending the stock plunging down to a low of $13.16 within the exact same day.
- The Day 1 Close ($24.39): After experiencing wild swings across a massive $79.58 intraday range, the initial wave of chaos began to settle, and the stock closed its first official day at $24.39.
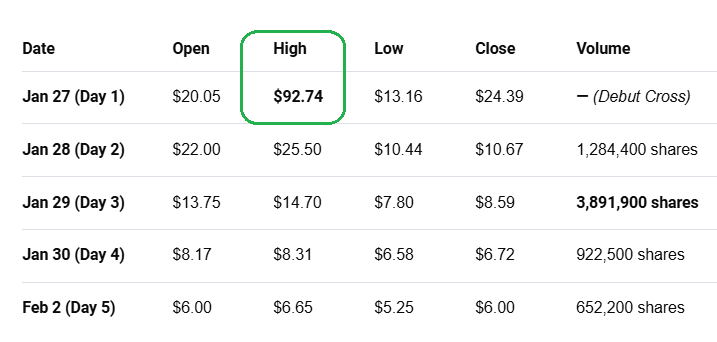
By day 5, traders who bought at $10 on day 2, sold to investors at $9.00, who sold to investors at $8.00, which repeated itself all the way down to $6.22, where investors who bought privately in the last round, hit breakeven. When they started selling, many who owned 2,000 shares or less, everyone else saw their Oculus dream go up in smoke.
To understand the madness of the day, being a direct listing with no big investment banks controlling the supply, almost immediately, a massive liquidity vacuum squeezed the stock up to an artificial, algorithmic high of $92.74.
It was complete market illusion. The second early crowd backers realized they were sitting on a $90 winning lottery ticket for an asset they bought for a fraction of that price, a tidal wave of selling pressure hit the book, flushing it down to $13.16 that same afternoon. By the time Day 3 rolled around, panic took over, volume exploded to 3.8 million shares, with the early trading retail crowd (at $20) completely washed out.
That initial chaos is exactly what cleared the deck for the smart money to walk in today. At this point, smart money looks at:
- A valuation near $30 million.
- Reviews of the Virtuix Experience – do the experts and user like or love it?
- A total addressable market of 20+ million users x product cost of $2,595 or $90 a month. Do the math with 5% penetration.
Finally smart money understands that Virtuix doesn’t have the hit or miss risk that VR software game makers have. Meta built a $100B+ ecosystem with 20M+ Quest headsets.
Virtuix doesn’t need to reinvent the wheel—they just need a tiny fraction of META Quest’s Top Titles to create a massive hardware business.
Eventually, the Smart Money Arrives? Why we Think Virtuix Rebounds.
In our eternal effort to uncomplicate a story, we use an analogy:
The “Movie Theater vs. Movie Studio” analogy.
We discussed what we beleive is the upside, as simple as we could. A great product and a massive market.
This section addresses some of the operational downsides. We won’t say ‘derisked’ because its still up to consumers, who would have to fork out $90 a month, to enjoy the totally immersive experience.
The “Movie Theater” Advantage: Why Virtuix Sidesteps Game Developer Risk
When investors look at the Virtual Reality and Spatial Computing sector, their minds often drift to high-risk software developers—studios spending tens of millions of dollars over 4-to-5-year development cycles, burning capital on massive engineering teams in hopes of creating a single breakout hit. Beat Saber with $250 million in sales in four years, shows it can be worth the risk.
However in gaming, as in Hollywood, binary content risk is brutal. A game can cost $50 million to make and still flop on launch day.
Virtuix is Not a Game Studio.
To understand Virtuix (VTIX), think of the company as the movie theater chain, not the film studio. Or note the fact that about one‑third to nearly half of U.S. households have a “home theater” in some form, which can range from $1,000 ro $50,000.
- Monetizing the Winner, No Matter Who Wins
A movie theater owner doesn’t care whether Disney, Universal, or an independent studio releases the summer’s top blockbuster—as long as audiences buy tickets, popcorn, and seats, the theater generates high-margin revenue. Similarly Virtuix doesn’t care which Titles META/Quest creates to become a top blockbuster.
As these titles get ‘better and better’ in the reality experience, the desire to own Omni One for the best experience, should only get ‘bigger and bigger.”
Virtuix operates on the exact same mechanics:
If Ghosts of Tabor is the top tactical shooter today, Omni One owners play it on the treadmill.
If a new studio launches a viral fitness hit tomorrow, players plug that in instead.
Virtuix captures the high-margin hardware sale ($2,595+ per unit) regardless of which software studio holds the #1 spot on the charts.
- $100 Billion in Free R&D and Marketing Leverage
Meta, Apple, Sony, and dozens of game publishers spend billions annually advertising VR gaming to the masses. Every time a major studio releases a trailer or spends millions marketing an active, motion-heavy VR game, they are effectively advertising a new reason to buy an Omni One. Virtuix piggybacks on Big Tech’s massive marketing spend without spending a single dollar on game production. - The Low-Penetration Thesis
Virtuix doesn’t need to sell 10 million units like Beat Saber to build a massive business. Beat Games Studio essentially built it ‘for them.’ Because the Omni One is a premium, full-body hardware platform, capturing just 0.1% to 1% of the active player base from existing Quest hits translates directly into thousands of high-ticket hardware sales.
The Takeaway for Investors:
Investing in game studios means betting on a single movie at the box office. Investing in Virtuix means owning the theater platform while the rest of the industry spends billions filling the seats.
We think once smart money investors (very few outside the gaming industry know about Virtuix) understand this dynamic and see (below) how it works in live action, you may agree with us, eventually “they will come.”
Expert Users Describe the Virtuix Experience. Learn How it Works, Without Buying One.
The Virtuix Virtual Reality Experience.
This is probably the most important part of this newsletter. It’s not financial. It tells you what the consumer is thinking. It’s not an easy read, with five videos lasting a couple hours, but worth every minute. Omni One is already a hit with gamers, influencers and ambassadors. And so there are hundreds if, not 1000’s of hours of videos on YouTube, reviewing the Omni One. And who has time for that?
It took hours for our guys to put this collection together, and we hope you enjoy it. Don’t try to watch all five in one sitting. These videos more than anything excite us most about Virtuix’s future. It even makes us want to buy one, for Fitness. We’ll issue a report on Fitness in the future. Just imagine, OMNI ONE + GLP 1. The fat will melt off.
SEE VIDEO COLLECTION: Video: Virtuix’s (VTIX) Omni One Tested, Tested and Then Tested Some More.
Original Report: Virtuix’s (VTIX) Full-Body Immersive Game Experience. Learn What we Like About Virtuix.
The revenue potential is equally simple, which could be generated by millions of users across the country and the world – who like in the photo below – enjoy running around in a virtual world. Literally.
The Virtuix Experience – is off of the couch and physically walking or running. And it doesn’t matter if it’s snowing or raining out, because it’s on a real treadmill in a virtual world, but in your living room. You could be working out and fighting dragons in your underwear. Great Christmas gift, and as we mentioned, they have a convenient payment plan for a little as $90 a month!
If you have any overweight gamers in your family, this is your chance. Break out the checkbook this Christmas.
Virtuix’s (VTIX) Full-Body Immersive Game Experience.
Brief History (11 Minutes) of the Virtual Reality Game Business.
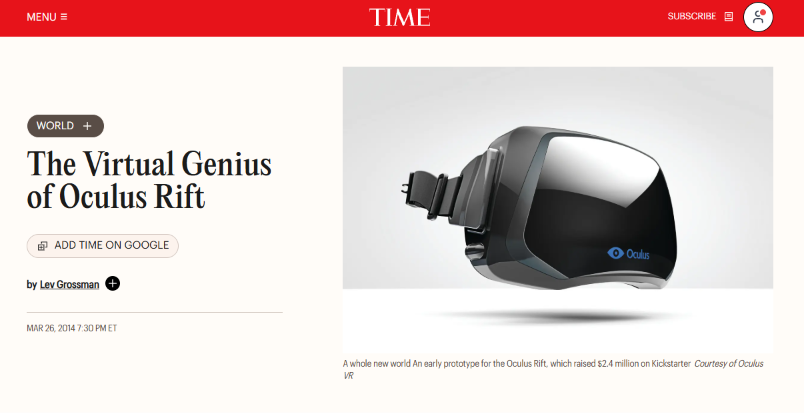
Story of Oculus: a $2 Billion META Aquisition in 2014, Worth $16 Billion Today. As in OMG
Oculus was acquired for roughly $2 billion by Facebook (now Meta) on March 25, 2014, with the deal officially closing on July 21, 2014. This included $400M in cash + $1.6B in Facebook stock, plus up to $300M in earn‑outs tied to milestones.
Breakdown of the deal
- Announced: March 25, 2014
- Closed: July 21, 2014
- Total value: ~$2,001,985,000
- Structure:
- $400M cash
- 23.1M shares of FB stock (~$1.6B)
- Up to $300M additional incentives (like who cares lol)
Everyone remembers Oculus as the ultimate crowdfunding fairy tale. They raised $2.4 million on Kickstarter back in 2012 and got scooped up by Mark Zuckerberg for a headline-grabbing $2 billion less than two years later.
But here’s the kicker: those original Oculus backers didn’t make a single dime on that buyout. Why? Because Kickstarter only allowed you to buy a ‘reward’—a prototype headset—not actual equity. The venture capital sharks stepped in right after, bought up the actual stock, and took most of the profit for themselves.
And what a profit it was. Zuckerberg paid the Oculus insiders $400 million in cold cash and handed them 23.1 million shares of Facebook stock. Back then, that stock package was worth $1.6 billion. Today, with Meta trading at an astronomical $736.72 a share, that exact same block of equity is worth over $17 billion! It stands as arguably the biggest, most explosive tech exit story in corporate history.
Virtuix is a completely different animal. Because of changes in modern equity crowdfunding laws, Virtuix’s 10,700 crowd backers actually bought real shares of stock. They got to own the very equity that the Oculus crowd was locked out of. But because they are everyday folks and not seasoned venture capital firms, they panicked when the public market got volatile. That retail exhaustion is what handed us this eighty-one cent entry point. The sharks got the $17 billion payday on Oculus; while the smart money arrives to scoop up potential payday on Virtuix in a couple years, fingers crossed.
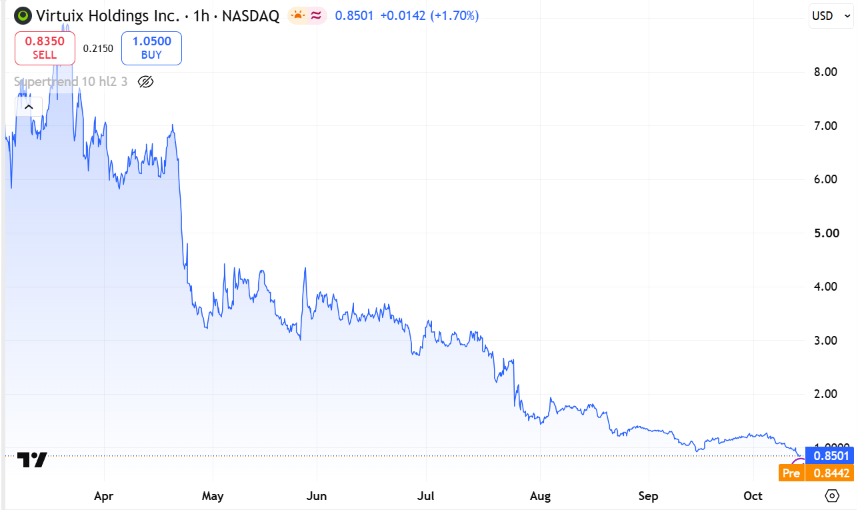
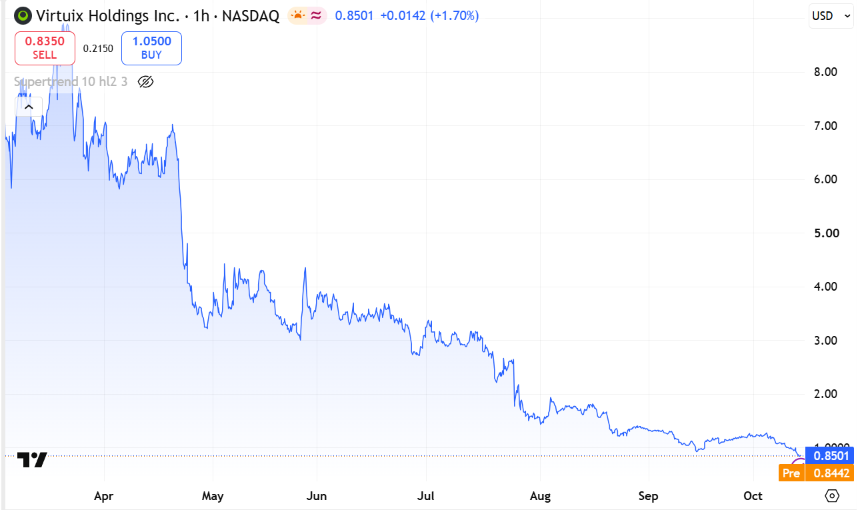
Recent Charts. Been a Rough Year!
Don’t say we didn’t tell you about this. We will be showing you this chart, exactly one-year from now.
SHORT TERM CHART
SIX MONTH CHART
About Virtuix
Virtuix Holdings Inc. (NASDAQ: VTIX) is a developer of AI-driven, full-body immersive simulation systems and the creator of the “Omni” omni-directional treadmill. Virtuix’s technology lets users physically move through virtual and AI-generated environments. The Company’s products are deployed across consumer entertainment, defense training and simulation, robotics, healthcare, research, and enterprise applications involving organizations including Meta, NASA, Tesla, KBR, and Sirica Therapeutics. The Company’s growing federal and defense footprint includes programs, deployments, and research initiatives involving the U.S. Army, Marine Corps, Navy, and Air Force.
Virtuix continues to expand the Omni brand from immersive entertainment into a broader, full-body simulation technology platform serving multiple commercial and government markets. For more information, visit virtuix.com or the Company’s new Investor Relations website at invest.virtuix.com.
Cautionary Note Regarding Forward-Looking Statements
This report and linked press releases contains “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements include, but are not limited to, statements concerning plans, objectives, goals, strategies, future events or performance, and underlying assumptions and other statements that are other than statements of historical facts. When the Company uses words such as “may,” “will,” “intend,” “should,” “believe,” “expect,” “anticipate,” “project,” “estimate,” “could,” “would,” “potential” or similar expressions that do not relate solely to historical matters, it is making forward-looking statements. Forward-looking statementsinclude, without limitation, statements regarding the Company’s sales and expansion plans, current and future game library, plans to pursue strategic acquisitions, potential impacts on future revenues or shareholder value, and the Company’s position in the defense training market. Forward-looking statements are not guarantees of future performance and involve risks and uncertainties that may cause the actual results to differ materially from the Company’s expectations discussed in the forward-looking statements. These statements are subject to uncertainties and risks including, but not limited to, the Company’s ability to identify, negotiate, and complete acquisitions on favorable terms or at all; the ability to successfully integrate any acquired business; risks related to government contracting, including contract cancellations, modifications, or funding changes; the uncertainties related to market conditions; and other factors discussed in the “Risk Factors” section of the Company’s registration statement filed with the SEC. For these reasons, among others, investors are cautioned not to place undue reliance upon any forward-looking statements in this press release. Additional factors are discussed in the Company’s filings with the SEC, which are available for review at www.sec.gov. The Company undertakes no obligation to publicly revise these forward-looking statements to reflect events or circumstances that arise after the date hereof. Not a client, yet.